
Compare Car Insurance Rates in Ohio
See if you qualify for a lower rate in less than 2 minutes



What Qualifies as Valid Proof of Insurance
Proof of insurance is documentation that verifies you have active auto coverage meeting your state's minimum requirements. Several types of documents qualify, and knowing the differences helps ensure you always have the right one on hand.
Insurance ID Card
The insurance ID card is the most common and convenient form of proof. This wallet-sized document contains your insurance company's name and NAIC number, your policy number, effective and expiration dates, vehicle details (year, make, model, and VIN), and the policyholder's name. Most insurers mail these cards twice yearly when issuing or renewing policies.
Your insurance card serves as quick verification during routine situations like traffic stops or basic DMV transactions. Keep your current card accessible at all times, and discard expired cards to avoid confusion. For a deeper breakdown of everything on your card, see our car insurance ID card guide.
Digital Proof of Insurance
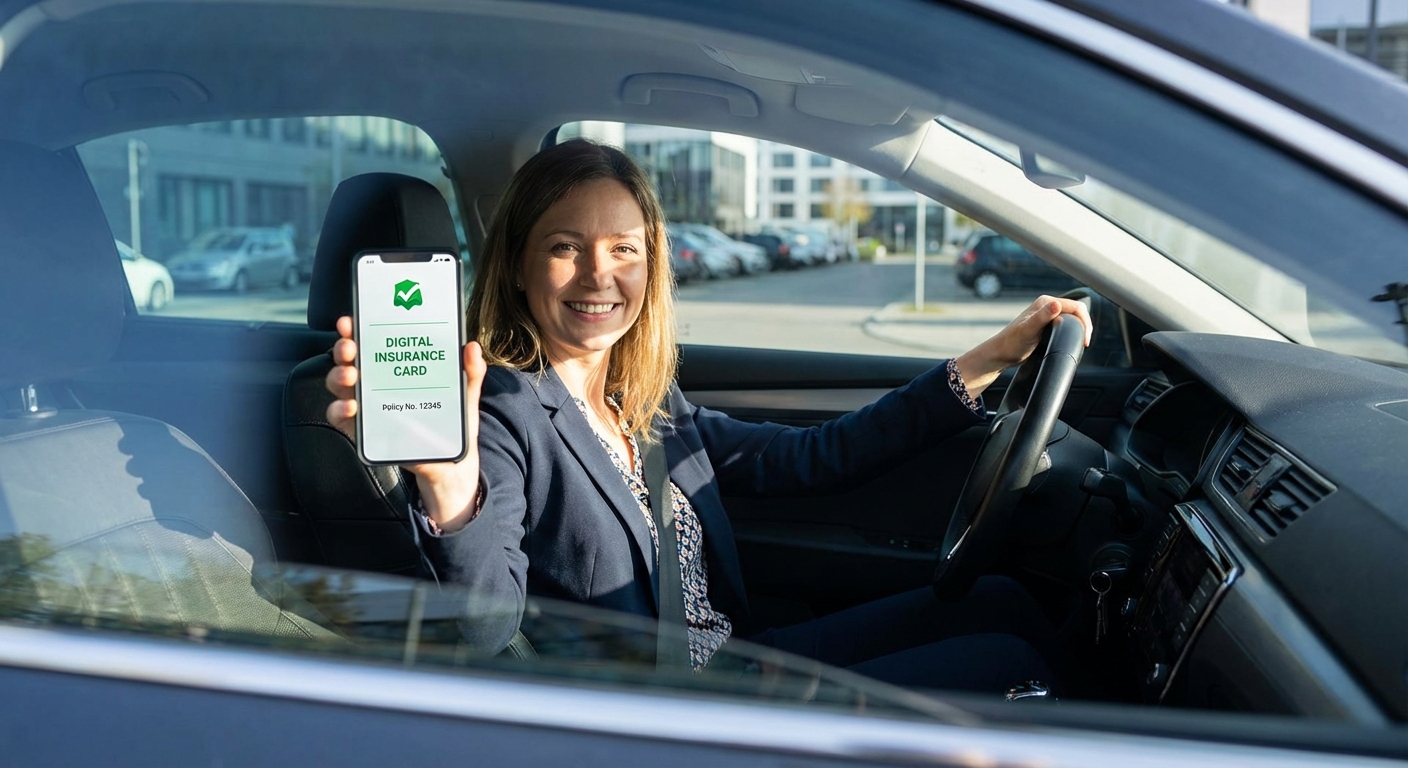
Digital proof has become the standard across the United States. According to 2026 industry data from Allstate, State Farm, and Insurify, 49 states plus Washington D.C. formally accept digital insurance cards on smartphones or tablets as valid proof at traffic stops and most DMV transactions. New Mexico remains the sole holdout where officers are not required to accept a phone display as proof, so a paper backup is still safest there or when traveling through the state.
Digital cards offer significant advantages including 24/7 accessibility through your insurer's mobile app, no risk of losing or forgetting physical cards, instant updates when policy details change, and the ability to share proof electronically with third parties. Most major insurers now provide dedicated apps that store your insurance information securely, and many support Apple Wallet and Google Wallet integration for one-tap access. You can learn more about the digital proof of insurance rules and accepted formats by state.
Declaration Page Explained
The declarations page provides comprehensive details about your policy that go far beyond a basic insurance card. This 1 to 2 page document includes all insured parties and vehicles, specific coverage types with their limits, deductibles for each coverage, premium amounts and payment schedule, policy endorsements and exclusions, and lienholder or lessor information.
While an insurance card proves you have coverage, the declaration page shows exactly what coverage you carry and at what limits. This distinction becomes critical when lenders, dealerships, or the DMV need to verify you meet specific coverage requirements, particularly since several states updated their minimums in 2025 and 2026. A dec page can also be used as proof of residency in certain scenarios where an ID card alone would not suffice.
Insurance Binders and Temporary Proof
An insurance binder serves as temporary proof of coverage while your permanent policy documents are being processed. When you purchase a new policy, your insurer immediately issues a binder that is typically valid for 30 to 90 days until your formal policy takes effect. State-specific caps include Texas at 30 days, Florida at 60 days, California and Georgia at 90 days by statute, and Utah allowing extensions up to 150 days. Some insurers issue binders for as little as 10 days.
Binders contain the same basic information as insurance cards and carry full legal authority as proof of insurance. They are particularly useful when buying a car or switching insurers, as you receive protection instantly without waiting for printed cards to arrive.

Compare Car Insurance Rates in Ohio
See if you qualify for a lower rate in less than 2 minutes
Where You Need Proof of Insurance
Understanding where you will need to present proof of insurance helps you stay prepared and avoid legal complications. Different situations may require different types of documentation.
During Traffic Stops
Law enforcement officers can request proof of insurance during any traffic stop, regardless of the reason for the stop. This is standard procedure in all 50 states. Officers need to verify that you are legally operating your vehicle with required insurance coverage.
Most police departments now accept digital proof displayed on smartphones. New Mexico remains the one state where the law does not explicitly authorize digital-only proof, so a physical card is still safest. When presenting digital proof, open the insurance app before the officer approaches your window to avoid appearing distracted.
It is worth noting that ALPR technology is now deployed by roughly 40% of U.S. law enforcement agencies as of mid-2026. ALPR cameras mounted on poles, traffic lights, overpasses, or patrol cars automatically capture license plates using OCR software, then cross-check them against hot lists and, in states with real-time electronic insurance databases (such as Missouri's MOIVS or Maryland's OLV), against coverage status. If a scanned plate returns a status of expired, missing, or uninsured, the system flags the vehicle in real time and alerts the officer, sometimes before a stop is even initiated. That means keeping your policy active is just as important as carrying valid proof. Learn more about how car insurance verification works from law enforcement's perspective.
Penalties for driving without proof vary significantly by state. Per WalletHub's 2026 state-by-state review, first-offense fines commonly start around $100 and can reach $1,000 to $5,000 in stricter states like Massachusetts, West Virginia, and Wisconsin, while Alabama's fine range for repeat offenders reaches $3,000. Repeat offenders can face SR-22 filings, multi-year suspensions, and in some states (Alabama, Arkansas, Georgia) potential jail time.
DMV Transactions and Vehicle Registration
State DMV offices require proof of insurance for multiple transactions including new vehicle registration, registration renewal, title transfers, license plate issuance, and obtaining or reinstating driver's licenses after certain violations. It is worth noting that car insurance and vehicle registration are tightly linked, and most states will not let you complete one without the other.
DMV requirements typically demand more detailed proof than traffic stops. Many states accept standard insurance cards, but some transactions require declaration pages to verify specific coverage limits. For example, when registering a financed vehicle, the DMV may need to confirm you carry collision and comprehensive coverage.
Car Dealership Requirements
Dealerships cannot legally allow you to drive a newly purchased vehicle off the lot without proof of insurance. This applies to both new and used car purchases from licensed dealers. Before finalizing your sale, you must provide documentation showing coverage effective immediately or at the time of purchase.
Most dealerships accept digital proof, but having a printed copy ready expedites the process. When purchasing a vehicle, contact your insurer beforehand to add the new car to your policy and receive instant proof. This preparation prevents delays at the dealership and ensures you can drive home immediately after purchase.
Lender and Lessor Verification
If you finance or lease your vehicle, your lender or lessor requires continuous proof that you maintain required insurance coverage. That means not just that you have insurance, but that your coverage includes collision and comprehensive protection sufficient to protect their financial interest.
When obtaining new insurance or switching companies, instruct your insurer to send proof directly to your lienholder. Most insurers handle this automatically, but confirming prevents potential issues. Lenders can force-place expensive insurance if they do not receive proof of your coverage, significantly increasing your costs.

Protect your car with Farmers
Average Rate:
Find coverage options that fit your budget.

The insurance savings you expect.
Average Rate:
Enjoy personalized policies, comprehensive coverage & more.

See how much you could save today!
Average Rate:
Drivers who switch their auto insurance and save with State Farm save $764 on average!

Safe Drivers Save with Allstate®
Average Rate:
Get rewarded with savings for having a clean driving record.
How to Obtain Proof of Insurance Instantly
Modern technology has made obtaining proof of insurance faster and more convenient than ever. Multiple methods provide instant access to valid documentation.
Through Mobile Insurance Apps
Nearly all major insurers provide digital ID cards via apps for instant access, alongside billing, policy servicing, and claims tracking. These apps support multiple formats: native in-app cards, downloadable PDFs, and mobile wallet integration for one-tap access. Key features include:
- 24/7 availability regardless of location or time of day
- Real-time updates when policy details change or renew
- Instant vehicle additions when you purchase a new car
- Quick sharing via email or text to dealerships and lenders
- Offline access via screenshots or saved PDF copies
Download your insurer's app immediately after purchasing coverage. Enable biometric login (fingerprint or face recognition) for instant, secure access during traffic stops without fumbling for passwords.
In 2026, GEICO, State Farm, and Progressive are effectively tied at the top of MarketWatch's mainstream insurer app rankings, each with a 4.6 out of 5 rating and more than 10 million downloads. Insurify's 2026 review puts State Farm, GEICO, Liberty Mutual, Progressive, and Farmers in a tie at 4.8 App Store / 4.6 Google Play, while The Zebra ranks USAA highest for user experience (though USAA is only available to military members and their families).
| Insurer | Digital Proof Feature | 2026 App Rating |
|---|---|---|
| GEICO | Instant ID card + DriveEasy telematics | 4.6/5 MarketWatch; 4.8 App Store per Insurify |
| State Farm | In-app ID card + Drive Safe & Save | 4.6/5 MarketWatch; 10M+ downloads |
| Progressive | Saveable ID cards + Snapshot integration | 4.6/5 MarketWatch; Apple Wallet support |
| Allstate | ID card + Drivewise + Milewise | 4.0/5 MarketWatch |
| USAA | ID card access + full policy management | Top user experience per The Zebra (military only) |
| Liberty Mutual | ID card access + RightTrack telematics | 4.8 App Store / 4.6 Google Play per Insurify |
Ratings based on 2026 App Store, Google Play, MarketWatch, Insurify, and The Zebra digital experience data.
Online Customer Portals
Every major insurance company maintains an online customer portal where policyholders can log in to view and download insurance documents. These portals offer the same information as mobile apps but through a web browser on any device.
Access your portal to download printable insurance cards, view and save declaration pages, update policy information, and request additional documentation. Keep your login credentials secure but readily accessible, and bookmark your insurer's portal for quick access.
Email and Phone Requests
If you do not have smartphone access or prefer traditional methods, contact your insurance agent or customer service directly. Most insurers can email proof of insurance within minutes of your request. Simply provide your policy number and verify your identity.
For urgent situations, agents can often fax proof to dealerships, DMV offices, or other parties requiring immediate verification. Keep your agent's contact information saved in multiple locations for emergency access.
Instant Proof at Purchase
When buying insurance online, virtually all insurers provide instant digital proof upon policy purchase. Coverage typically takes effect immediately, and you receive downloadable insurance cards through email confirmation and your newly created online account. To understand how quickly your policy actually goes live, see our car insurance waiting period guide.
This instant access proves invaluable when you need coverage immediately, such as buying a car after hours or on weekends. Many online insurers offer coverage purchase and activation in under 30 minutes. For a step-by-step walkthrough of buying a new policy, see our car insurance application guide.
Digital vs. Physical Insurance Cards by State
State acceptance of digital proof of insurance has expanded rapidly. As of 2026, 49 states plus D.C. formally accept digital cards, and while some industry sources now describe acceptance as effectively nationwide, New Mexico's statutes still leave the door open to citations for digital-only proof.
States Fully Accepting Digital Proof
At least 49 states plus Washington D.C. accept digital insurance cards displayed on smartphones or tablets as valid proof during traffic stops and most DMV transactions. Drivers in New Mexico should still keep a physical card as a safeguard.
States with full digital acceptance allow drivers to show insurance cards on any device including smartphones, tablets, and even smartwatches in some jurisdictions. Many insurers also support Apple Wallet and Google Wallet integration, making one-tap access to your digital card seamless.
New Mexico's Physical Card Requirement
New Mexico is the one state where digital proof is not formally authorized by statute. Drivers there should carry a printed insurance card, a copy of their policy, or a verification letter from their insurer. While some officers may informally accept digital displays, the law does not require it, and attempting to show digital proof during a traffic stop could result in a citation for failure to provide proper documentation.
If you live in or frequently travel through New Mexico, always keep physical insurance cards in your vehicle. Request duplicate cards from your insurer if needed, and ensure all drivers of your vehicle have access to physical documentation.
Massachusetts and New Hampshire Special Notes
Massachusetts uses a unique approach where proof of insurance is integrated into vehicle registration documents rather than requiring separate insurance cards. The state's RMV system electronically verifies insurance coverage, making separate proof documentation less critical for routine in-state transactions. GEICO also notes that both Massachusetts and New Hampshire do not accept the digital ID cards issued through GEICO Mobile, so carriers may vary in how they handle those two states.
However, Massachusetts residents should still obtain insurance cards from their insurers for use during traffic stops in other states or when moving to another state requires proof of prior coverage.
Best Practices for All States
Regardless of your state's official position on digital proof, maintaining both digital and physical copies provides optimal protection.
| Proof Type | Advantages | Limitations |
|---|---|---|
| Digital via App | Always accessible, automatic updates, wallet-ready | Requires charged phone, not statutorily authorized in New Mexico |
| Physical Card | Universally accepted, no technology required | Can be lost or forgotten, requires manual updates |
| Printed PDF | Backup option, works anywhere | Can become outdated, requires printing |
Understanding how your state's insurance verification system works can also help you stay compliant beyond just carrying the right card. Roughly 34 states now use some form of real-time or near-real-time electronic verification, with newer systems including Kansas SB 42 (fully operational by July 1, 2026), Missouri's MOIVS (launched March 16, 2026), Pennsylvania's Act 3 of 2026 giving PennDOT roughly 18 months to build its OLV system, Kentucky's HB 390 system operational by October 1, 2026, and New York targeting full implementation by December 31, 2028.
Temporary Proof When Switching Insurers
Switching insurance companies requires careful coordination to maintain continuous coverage and valid proof throughout the transition.
Obtaining Immediate Coverage
When switching insurers, your primary concern should be avoiding coverage gaps that could result in higher future insurance rates or license suspension. Purchase your new policy with an effective date that matches or precedes your old policy's cancellation date.
Most online insurance platforms provide instant policy purchase and immediate digital proof. This allows you to complete the switch outside business hours without waiting for physical documentation. Having a proof of prior insurance letter from your old insurer can also help qualify you for loyalty or continuous coverage discounts with your new carrier.
Download Digital Proof Immediately
As soon as you complete your new policy purchase, access your digital insurance cards through your new insurer's mobile app, online portal, or email confirmation. Download or screenshot these documents to ensure access even if you experience connectivity issues later.
Save digital proof in multiple locations including your smartphone's photo gallery, email folders, and cloud storage services. Label saved files with the policy term (e.g., "Auto-Card-2026-2027") so you always know which copy is current.
Coordinate Cancellation Timing
Never cancel your old insurance policy before your new coverage begins. Proper cancellation timing ensures continuous coverage and maximizes any refund you are owed for unused premium.
Contact your old insurer to schedule cancellation effective the same day your new policy begins. Request written confirmation of the cancellation date and any refund amount. Most insurers process refunds within 7 to 14 business days through your original payment method.
Notify Your Lender Promptly
If you finance or lease your vehicle, inform your new insurer of your lienholder's information immediately. The insurer should automatically send proof of insurance to your lender, but verifying this happens prevents potential complications.
Lenders typically require notification within 30 days of policy changes. Failure to provide updated insurance information can result in force-placed insurance, where the lender purchases expensive coverage on your behalf and charges you for the premium.
Consequences of Not Having Proof of Insurance
Failing to provide proof of insurance carries serious financial and legal consequences that extend beyond simple citations.
Traffic Stop Penalties and Fines
When you cannot provide proof of insurance during a traffic stop, officers issue citations regardless of whether you actually have coverage. In many states, if you later show valid proof in court, the citation is reduced or dismissed. If you truly had no coverage, penalties escalate quickly. WalletHub's 2026 state-by-state review shows first-offense fines commonly ranging from $100 to $1,000, with Massachusetts, West Virginia, and Wisconsin reaching up to $5,000, and Alabama exposing repeat offenders to 3 to 6 months in jail plus fines up to $3,000. Georgia layers on a 60-day license and registration suspension plus up to 12 months of jail exposure for driving uninsured.
Citations typically require court appearances where you must present evidence of insurance coverage. Even if you prove you had valid insurance at the time of the stop, courts may still impose reduced fines or administrative fees. Multiple violations result in progressively higher penalties and potential license suspension.
License and Registration Suspension
Many states impose license suspension for repeated proof of insurance violations or if you cannot demonstrate coverage when required. Suspension periods typically range from 30 days to one year depending on violation history and state laws. In Arizona, first offenders face a 3-month suspension of their license, registration, and plates, while repeat offenders face 6 to 12 months. In Mississippi, a single conviction can trigger a one-year license suspension.
Registration suspension prevents you from legally operating your vehicle until you restore compliance. This requires paying reinstatement fees (often $50 to $500, with Alabama charging $200 to $400 depending on offense), providing proof of current insurance, and sometimes filing SR-22 certificates.
Vehicle Impoundment Risk
In serious cases or when combined with other violations, inability to provide proof of insurance can result in immediate vehicle impoundment. Law enforcement may tow your vehicle from the traffic stop location, requiring you to pay towing fees, daily storage charges, and impound release fees before retrieving it.
Impoundment costs quickly escalate, often reaching $500 to $1,000 within the first week. You must provide valid proof of insurance and pay all fees before the impound facility releases your vehicle.
Insurance Rate Increases
Citations for failure to provide proof of insurance appear on your driving record and impact your insurance premiums. While less severe than DUI or at-fault accidents, these violations signal risk to insurers and typically increase rates by 10 to 20% for three to five years.
The increased premiums cost far more than the original citation. A driver paying $1,500 annually could face an additional $150 to $300 per year in higher premiums, totaling $450 to $1,500 over three years, just for not having proof readily available.
If you ever need to confirm someone else's coverage after an accident or purchase, our guide on how to check if a car has insurance walks through five legal verification methods.
Frequently Asked Questions
Can police officers accept digital proof of insurance in all states?
49 states plus Washington D.C. formally accept digital insurance cards, and recent industry reporting suggests digital proof is now permitted in practice nationwide. New Mexico is the one state where the law does not explicitly authorize digital-only proof, so a physical backup is safest there. Additionally, ALPR cameras used by roughly 40% of U.S. law enforcement agencies cross-check your plate against hot lists and, in some states, electronic insurance databases in real time. Even in states accepting digital proof, keeping a physical backup card in your vehicle protects you if your phone dies or malfunctions.
What is the difference between an insurance ID card and a declarations page for proof purposes?
An insurance ID card provides basic information like your policy number, coverage dates, vehicle details, and insurer contact information for routine verification during traffic stops or simple DMV transactions. The declarations page is a comprehensive document showing specific coverage types, limits, deductibles, premiums, and endorsements, and it is typically required by lenders, dealerships, or when registering vehicles that need verified coverage levels. Think of the ID card as quick proof you have insurance while the declarations page proves exactly what insurance you carry. You can also review our car insurance ID card guide for a full breakdown of what each document contains.
How quickly can I get proof of insurance if I lost my card?
You can obtain replacement proof instantly through your insurer's mobile app or online customer portal. Simply log in and view or download your current insurance card with no waiting period. Alternatively, contact your agent or customer service by phone or email, and most insurers can send digital proof within minutes. If you need physical cards, insurers typically mail replacements within 5 to 7 business days, but digital options eliminate any waiting time entirely.
What penalties do I face if I cannot show proof during a traffic stop?
Penalties vary widely by state. If you can later prove you had valid coverage, most states reduce the citation to a small administrative fine. If you were actually uninsured, WalletHub's 2026 review shows fines commonly running from $100 to over $1,500, with Massachusetts, West Virginia, and Wisconsin reaching up to $5,000 and some states requiring SR-22 filings for two to three years. Multiple violations can also result in license suspension for 30 days to one year, vehicle registration suspension, jail exposure in states like Alabama, Arkansas, and Georgia, and premium increases of 10 to 20% for three to five years.
Can I get temporary proof immediately when switching insurance companies?
Yes. When you purchase a new policy online, virtually all insurers provide instant digital proof through email confirmation, mobile app access, or downloadable PDF cards that you can use immediately. Make sure to also request a proof of prior coverage letter from your old insurer, as this document can help you qualify for continuous coverage discounts with your new carrier. Never cancel your old policy before your new one is active, since coverage gaps can raise your premiums significantly, as we cover in our guide on the car insurance waiting period.