
Compare Home Insurance Plans in Ohio
Find your best options in less than 2 minutes

What Is Hippo Home Insurance?
Hippo launched in 2015 with a bold promise: to modernize homeowners insurance by making it faster, smarter, and more proactive than traditional carriers. Instead of the reactive, paper-heavy model that most legacy insurers use, Hippo built its model around technology, offering instant online quotes, smart home device integration, and proactive monitoring tools designed to help prevent claims before they happen.
Unlike many companies that both sell and underwrite policies, Hippo operates as an insurtech platform. Policies are underwritten by partner carriers, most notably Spinnaker Insurance Company, along with additional third-party carriers matched to eligible customers. This means Hippo handles the customer experience and technology while licensed carriers back your actual policy. As of April 2026, Hippo operates in states including AZ, CA, CO, CT, FL (limited), GA, IL, MD, MI, MN, MO, NJ, NV, NY, OH, OR, PA, TN, TX, VA, WA, and WI, with distribution further expanded through a strategic relationship with Progressive Advantage Agency that added Hippo products to Progressive's HomeQuote Explorer in eight states: Colorado, Georgia, Illinois, Ohio, Pennsylvania, South Carolina, Tennessee, and Texas. As of mid-2026, most new Hippo customers are matched with third-party insurance carriers rather than getting a Hippo-underwritten policy through Spinnaker Insurance, as Hippo has selectively resumed writing its own policies with limited availability.
Coverage Options at a Glance
Hippo policies follow a standard HO-3 style structure, but with meaningfully higher base limits for tech-heavy households:
| Coverage Section | What It Includes |
|---|---|
| Dwelling (A) | Cost to rebuild your primary structure after a covered loss |
| Other Structures (B) | Fences, sheds, detached garages |
| Personal Property (C) | Furniture, electronics, appliances, home office gear |
| Loss of Use (D) | Additional living expenses if your home is uninhabitable |
| Personal Liability (E) | Injury or property damage you're legally responsible for |
| Medical Payments (F) | No-fault medical coverage for injured guests |
Hippo's base personal property coverage is notably higher than typical policies. While most standard policies default to 25 to 30 percent of dwelling coverage, Hippo starts at 50 percent or more. Unlike other insurers, all Hippo home insurance policies provide up to $100,000 of appliance coverage to repair or replace units damaged by electrical or mechanical breakdown. Common optional endorsements include water backup, service line coverage, and extended reconstruction cost.
Compare Home Insurance Plans in Ohio
Find your best options in less than 2 minutes
Hippo's Smart Technology & Proactive Risk Management
This is where Hippo truly differentiates itself from both traditional insurers and other insurtechs. Rather than waiting for something to go wrong, Hippo's model is built around preventing losses in the first place.
Smart Home Integration
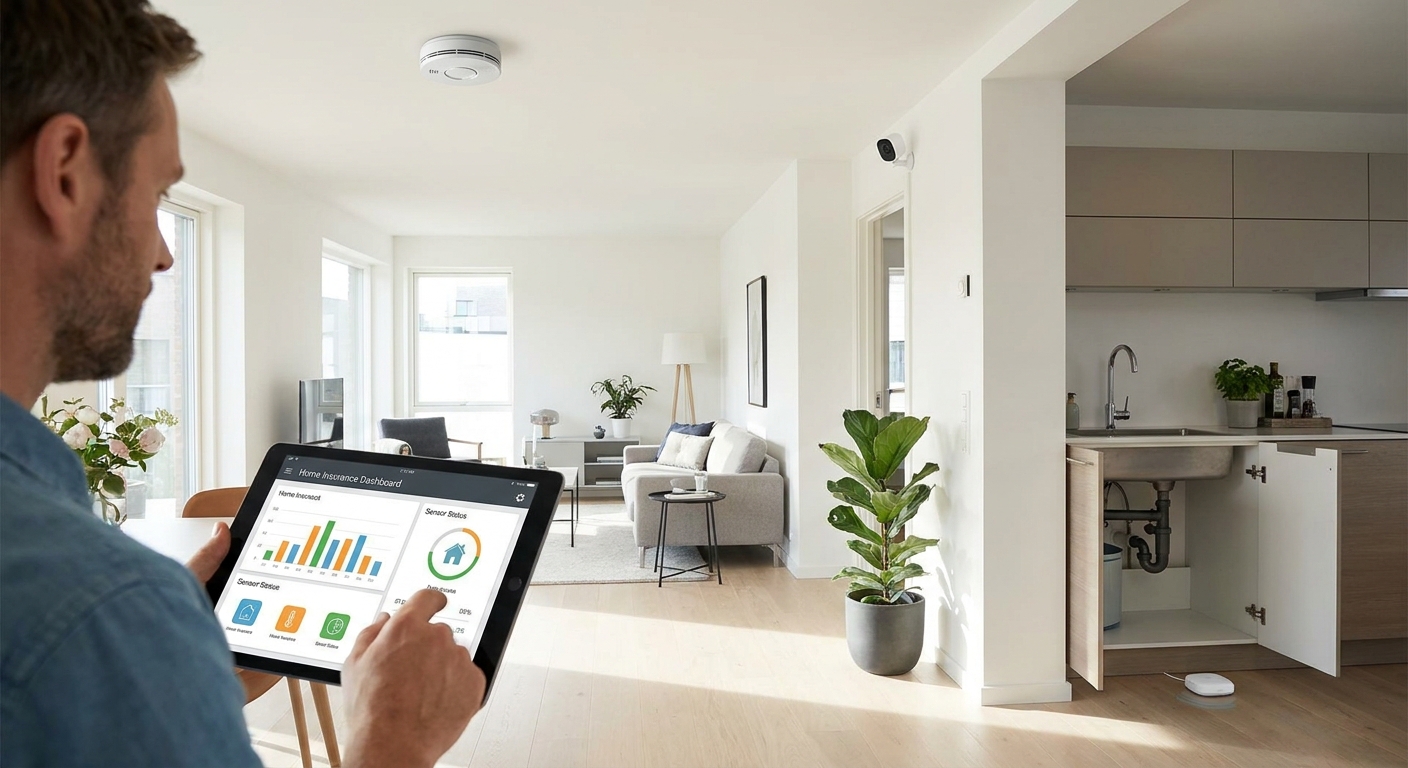
Hippo says customers with a smart home discount save an average of $64 per year with a self-monitoring kit and $91 per year with a professionally monitored kit, and the discount is included in the premium as long as the system stays activated year after year. Hippo now runs what it calls the most widely adopted smart home program in homeowners insurance, with more than 500,000 sensors deployed across its customer base. In select markets, Hippo has partnered with companies like ADT, SimpliSafe, and Ring to offer professionally installed and monitored systems that unlock these discounts.
Qualifying devices typically include:
- Water leak sensors to detect moisture before it becomes major damage
- Smoke and CO detectors for early warning on fire-related losses
- Entry sensors and security cameras from brands like Ring, SimpliSafe, and ADT
Hippo's Proactive Risk Philosophy
Hippo's approach to risk management is notably different from legacy carriers. The company uses AI-driven underwriting and real-time data signals to assess risk more dynamically. It has also implemented selective underwriting, including rate adjustments, higher wind/hail deductibles in vulnerable regions, and non-renewals in the highest-risk areas, to keep the portfolio financially healthy.
This risk-first mentality has produced real financial results. In Q2 2026, Hippo reported net income of $10 million (or $0.38 per diluted share) and adjusted net income of $21 million, with gross written premium reaching $482 million (61% year-over-year growth) and an improved combined ratio of 95.8%, marking its fifth consecutive profitable quarter. Adjusted earnings of $0.79 per share topped Wall Street's forecast of a $0.18 loss, and the company raised both its full-year 2026 guidance and long-term 2028 targets.
For a comparison with another digital-first carrier, check out our Lemonade home insurance review to see how these two insurtechs stack up. You can also learn more about qualifying smart home insurance discounts across major carriers.

Protect your home with State Farm
Average Rate:
Homeowners who bundle and save with State Farm save an average of $1,000 per year!

You're in Good Hands® with Allstate
Average Rate:
Get comprehensive home coverage with flexible policy options.

Customize your home coverage
Average Rate:
Only pay for the coverage you need with personalized home insurance.

Smart coverage for your home
Average Rate:
Protect what matters most with award-winning home insurance.
Hippo Home Insurance: Pros, Cons & Customer Ratings
Customer Ratings Summary (2026)
Hippo's ratings are a tale of two extremes. Its mobile apps are well-loved, while third-party review platforms tell a more sobering story:
| Rating Source | Score | Notes |
|---|---|---|
| Trustpilot | 2.1 to 3.2 / 5 | Mixed; claims and cancellation complaints dominate |
| BBB Customer Reviews | ~2.66 / 5 | A- business rating, 136 complaints in 3 years |
| The Zebra (2026) | 1 / 5 | Rated "subpar" overall |
| ValuePenguin (Editorial) | 4.0 / 5 | Praises pricing and digital experience |
| Way.com Satisfaction | 3.8 / 5 | Mixed reviews, no J.D. Power data |
| AM Best (Spinnaker) | A- (Excellent) | Financial strength affirmed January 2026 |
One 2026 review summary reports a Trustpilot rating of 2.1/5, a BBB customer rating of 2.66/5 with 136 complaints in three years, and an AM Best A- (Excellent) financial strength rating for primary underwriter Spinnaker, affirmed January 2026. The Zebra rates Hippo 1/5 as a "subpar" insurance company, while noting a Trustpilot score of 3.2/5 and BBB rating of 2.66/5 from users. The disconnect between editorial scores and user reviews is significant.
Common Complaints
Common complaint themes include slow or difficult claims resolution, trouble canceling policies, delayed refunds, poor communication, and dissatisfaction after losses. One 2026 review says Hippo's underwriting subsidiary Spinnaker had a 2024 NAIC complaint index of 4.45, described as the second-worst in the homeowners industry.
Common themes in negative reviews:
- Sharp premium increases at renewal, particularly in high-risk states
- Claims delays, with reports of waits lasting weeks to months
- Poor communication from adjusters and support staff after purchase
- Denial disputes, including complaints about intrusive underwriting photo requests
Hippo's Pros and Cons
How Much Does Hippo Home Insurance Cost in 2026?
Hippo's average annual premium is roughly $1,761 per year (about $147 per month), which is roughly 17% cheaper than competitor pricing. That still compares favorably to the industry benchmark. Policygenius reports a national average Hippo cost of $1,138 per year for a $300,000 dwelling policy, about 40% cheaper than the national average at that coverage level. However, actual pricing varies dramatically by state. In Texas, for example, the state average home insurance cost is $4,085 in 2025, down from $4,437 in 2024, illustrating just how much premiums can shift in high-risk markets.
Your actual premium depends on your home's location, age, size, roof condition, claims history, and which coverage limits and endorsements you select. To get a full picture of the price landscape, check our guide on cheap home insurance and 17 ways to lower your home insurance premium.
Hippo vs. Lemonade vs. Traditional Insurers
Both Hippo and Lemonade are insurtechs targeting homeowners who prefer a digital experience over working with agents. But they take meaningfully different approaches.
| Feature | Hippo | Lemonade | Traditional Insurer |
|---|---|---|---|
| Online Quote Speed | ~60 seconds | ~90 seconds | Varies (agent often required) |
| Smart Home Discounts | Yes, $64 to $91/year average | Limited | Rarely |
| Water Backup Coverage | Often included in policy | Add-on cost | Add-on cost |
| Auto Bundling | Not available | Available | Usually available |
| Product Range | Homeowners only | Home, renters, auto, pet, life | Full lines |
| State Availability | ~22 to 37 states + 8 via Progressive | 30 states + D.C. | Varies |
| Underwriter | Spinnaker + partner carriers | Lemonade + partners | Varies |
Hippo tends to include more coverage up front, with water backup, ordinance or law, and extended reconstruction typically built into its standard policy tiers, while Lemonade often offers those same protections as endorsements. Lemonade offers renters, homeowners, life, pet, and car insurance, while Hippo currently only offers homeowners insurance, so bundling and multi-product relationships are only possible with Lemonade.
Key takeaway: Hippo is better suited for tech-savvy homeowners who want proactive protection and built-in extras like water backup. Lemonade appeals to those who want a fully app-driven experience with bundling options. If you want the reliability of a long-established carrier, consider reviewing our Progressive homeowners insurance review or our Geico home insurance review.
Frequently Asked Questions (FAQ)
Is Hippo home insurance good in 2026?
Hippo is a reasonable option for tech-forward homeowners who value digital convenience, smart home discounts, and proactive protection tools. Pricing tends to run below industry averages, and its financials have turned decisively profitable with five straight quarters of profitability through Q2 2026. However, mixed to negative customer reviews and Spinnaker's elevated NAIC complaint index (4.45 in 2024) mean it may not be ideal if you prioritize hands-on claims support.
What states does Hippo home insurance operate in?
Hippo's own homeowners products are active in roughly 22 to 37 states depending on the source and product mix, including AZ, CA, CO, CT, FL (limited counties), GA, IL, MD, MI, MN, MO, NJ, NV, NY, OH, OR, PA, TN, TX, VA, WA, and WI. Its products are also distributed through Progressive's HomeQuote Explorer in eight states. Availability can change quickly, so always start a quote to confirm eligibility in your state.
How much does Hippo home insurance cost?
Hippo policies average roughly $1,761 per year (or about $147 per month), which is around 17% below competitor pricing and well below the national average of about $2,490 per year for comparable coverage. At $300,000 dwelling coverage specifically, Policygenius reports Hippo at $1,138 per year, about 40% cheaper than the national average. Your actual premium will vary based on your home's location, age, roof condition, claims history, and which endorsements you add.
How does Hippo compare to Lemonade home insurance?
Both are insurtechs offering fast digital quotes, but Hippo's strength is proactive risk tools, smart home integration, and built-in extras like water backup and up to $100,000 of appliance breakdown coverage. Lemonade has an edge in bundling because it also offers renters, pet, life, and auto coverage, plus a fully app-driven claims process for small claims. Hippo is homeowners-only, so if you want a single-brand relationship across multiple lines, Lemonade wins.
What are the most common Hippo home insurance complaints?
The most frequently reported complaints involve slow or difficult claims resolution, trouble canceling policies, delayed refunds, poor adjuster communication, and disputes over claim denials. Spinnaker's 2024 NAIC complaint index of 4.45 was described in one 2026 review as the second-worst in the homeowners industry. Because Hippo may route your policy to Spinnaker or to a third-party partner carrier, always ask which underwriter is assigned before you bind.