
Compare Car Insurance Rates in Ohio
See if you qualify for a lower rate in less than 2 minutes



Why Apples-to-Apples Comparison Is the Only Way to Shop Smart
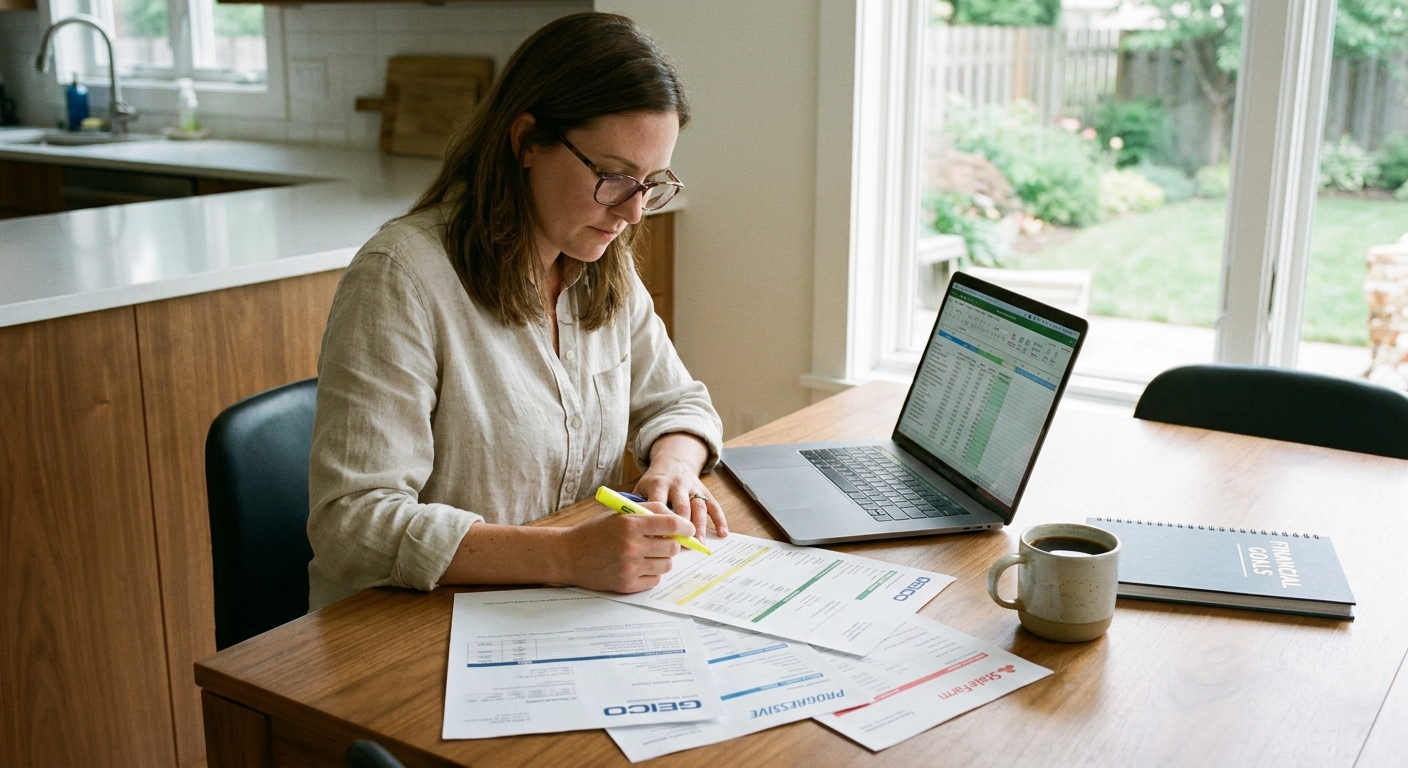
Comparing car insurance quotes without matching your coverage is like comparing the price of a sports car to a compact sedan. The numbers mean nothing without the same baseline. An apples-to-apples car insurance comparison means requesting quotes from multiple insurers using the exact same liability limits, deductibles, and optional coverages so you're measuring actual price differences, not just coverage trade-offs.
In 2026, this matters more than ever. According to Insurify's August 2026 data, the national average for full-coverage car insurance is $187 per month (about $2,237 per year, up 1% since the end of 2025). Other sources come in higher: NerdWallet at $2,356, The Zebra at $2,256 (up 3% year over year), and ValuePenguin at $2,496 per year. What's unusual about this year is that rate changes are running in opposite directions across carriers. State Farm has cut auto rates in about 40 states averaging roughly 10%, delivering approximately $4.6 billion in annual customer savings. In Florida alone, the top five carriers (Progressive, Berkshire Hathaway/GEICO, State Farm, Allstate, and USAA) cut premiums by an average of 8% in early 2026, with Allstate down 7% and State Farm's Florida reductions totaling more than 20% since fall 2024. If you're only comparing two carriers in this environment, you're leaving real money on the table.

Compare Car Insurance Rates in Ohio
See if you qualify for a lower rate in less than 2 minutes
The Core Variables You Must Match Exactly
To make a fair comparison, every quote you request must use the same inputs. Here's what to standardize before you start shopping.
Liability Limits
Liability coverage is expressed as three numbers (e.g., 100/300/100), representing:
- Bodily injury per person (e.g., $100,000)
- Bodily injury per accident (e.g., $300,000)
- Property damage per accident (e.g., $100,000)
Never compare a quote with 25/50/25 limits to one with 100/300/100. The premium difference reflects coverage, not insurer pricing. Most financial experts recommend at least 100/300/100 limits for adequate protection in 2026, and drivers with significant assets should consider 250/500/250 plus an umbrella policy. Note that New Jersey raised its state minimum to 35/70/25 effective January 1, 2026, and Hawaii moved to 40/80/20 the same day, joining California (30/60/15), Utah, Virginia (50/100/25), and North Carolina (50/100/50), which updated their minimums in 2025. Learn more about what car insurance covers to choose the right limits before you shop.
Deductibles
Your collision and comprehensive deductibles directly affect your premium. A $250 deductible quote will always cost more than a $1,000 deductible quote, even from the same company. Set the same deductible amount (most commonly $500 or $1,000) across every quote you collect. Roughly 26% of policyholders now carry $1,000+ deductibles to offset rising premiums per CCC Crash Course 2026 data. Understanding how premiums are calculated in depth will help you choose wisely before locking in comparisons.
Optional Coverages
These add-ons vary by insurer and can quietly inflate or deflate a quote:
- Uninsured/Underinsured Motorist (UM/UIM)
- Personal Injury Protection (PIP)
- Roadside Assistance
- Rental Reimbursement
- Gap Insurance

Protect your car with Farmers
Average Rate:
Find coverage options that fit your budget.

The insurance savings you expect.
Average Rate:
Enjoy personalized policies, comprehensive coverage & more.

See how much you could save today!
Average Rate:
Drivers who switch their auto insurance and save with State Farm save $764 on average!

Safe Drivers Save with Allstate®
Average Rate:
Get rewarded with savings for having a clean driving record.
How to Build Your Comparison Spreadsheet
A simple spreadsheet eliminates confusion and makes patterns obvious. Use Google Sheets or Excel and organize it with these columns:
| Data Point | What to Record |
|---|---|
| Company Name | Insurer and quote reference number |
| Quote Date | Quotes typically expire in 15 to 30 days |
| Monthly / Annual Premium | Normalize all to annual for fair math |
| Bodily Injury Liability | e.g., 100/300 |
| Property Damage Liability | e.g., $100,000 |
| Collision Deductible | e.g., $500 |
| Comprehensive Deductible | e.g., $500 |
| UM/UIM Coverage | Included or excluded |
| PIP / MedPay | Limit amount |
| Roadside / Rental | Yes/No and limit |
| Discounts Applied | List each discount |
| AM Best Rating | Financial strength grade |
| J.D. Power Score | Customer satisfaction rating |
| NAIC Complaint Index | Below 1.0 is favorable |
Once populated, sort by annual premium, but never choose on price alone. The last three rows (AM Best, J.D. Power, NAIC) are just as important as the dollar amount. For a deeper walkthrough, see our car insurance policy review checklist.
Common Mistakes That Skew Your Comparison
Even well-intentioned shoppers make these errors regularly:
One of the biggest overlooked mistakes is entering inaccurate information on quote forms. If you underreport your annual mileage or omit a past accident, the quote won't reflect your actual premium. You'll be blindsided at purchase. Learn why car insurance quotes change after the initial estimate so you know what to expect.
Why Do Quotes Differ Even for the Same Coverage?
Even with identical inputs, two insurers can quote dramatically different prices. This happens because each company uses its own proprietary risk models. Key factors that affect rates and get weighed differently include:
- Credit-based insurance scores. Some carriers penalize poor credit far more than others, with poor-credit drivers paying 69% to 98% more than good-credit drivers. Only four states (California, Hawaii, Massachusetts, and Michigan) fully ban this practice.
- Geographic risk weighting. ZIP code-level loss data varies significantly by insurer.
- Customer profile targeting. Companies specialize in certain driver types.
- Rate strategy divergence. In 2026, State Farm is cutting rates by an average of 10% across 40 states (with recent approved reductions of 6.2% in California effective May 8, 2026, 4.1% in Texas, 8% in South Carolina, and 5.9% in Louisiana), while some competitors continue to raise premiums in specific states.
This is precisely why comparing quotes from multiple sources, not just one or two, is so important. According to a Consumer Reports survey of over 40,000 policyholders, the median annual savings for drivers who switched insurers was $461, with 41% of switchers saving $500 or more per year and 13% saving over $1,000. A separate LendingTree survey found that 92% of Americans who switched carriers saved money, with typical annual savings of $400 to $900 depending on location. In expensive markets like Florida, New York, and Michigan, switching savings often reach $700 to $900 a year. Learn more in our guide on how to switch car insurance.
Beyond Price: What Else to Evaluate
A lower premium is worthless if your insurer fails you at claim time. Here's how to evaluate the non-price factors that define true value:
Financial Strength Ratings
AM Best ratings of A or higher indicate an insurer can reliably pay claims even during high-loss periods. Note that State Farm Mutual was downgraded from A++ to A+ on November 14, 2025, citing five consecutive years of underwriting losses driven by tough auto and home results, heavy catastrophe losses, and regulatory constraints, though it remains in AM Best's Superior category with a Stable outlook. State Farm General (its California subsidiary) sits at B (Fair) after a March 2024 downgrade. USAA, Travelers, and GEICO remain at A++, while Erie sits at A after a September 2025 adjustment. Avoid any company rated below B+. Check out our guide on company reputation and reviews for a full breakdown of how to use these ratings.
Claims Satisfaction
The most recent J.D. Power U.S. Auto Claims Satisfaction Study set the industry average at 700 out of 1,000, up 3 points year over year. Erie Insurance led at 743, followed by NJM Insurance (731) and Liberty Mutual (730), while Safeco (672) and National General (605) ranked at the bottom. The June 2026 J.D. Power U.S. Auto Insurance Study found overall satisfaction with auto insurers holding steady at 644 out of 1,000. A record 57% of customers shopped their coverage and 29% switched carriers, showing that price satisfaction is improving as fewer customers report premium increases. A company scoring below 650 on the claims study should raise a red flag regardless of its premium.
NAIC Complaint Index
The National Association of Insurance Commissioners publishes a complaint index for every licensed insurer. A score below 1.0 means the company receives fewer complaints than average for its size. Recent NAIC data shows Nationwide (0.34), Erie (0.35), Travelers (0.49), GEICO (0.62), and State Farm (0.70) all well below average, while Liberty Mutual (2.46) and Infinity (2.83) sit well above it. This metric is especially valuable for spotting claims-handling disputes before you commit to a policy.
Step-by-Step Guide: Running an Accurate Quote Comparison
Follow these steps in order to ensure a genuinely fair comparison:
- Pull your current declarations page. Record your exact coverage types, limits, and deductibles. This is your baseline.
- Decide on your target coverage level. If you want to improve coverage, lock in new limits before shopping.
- Gather your information. You'll need your driver's license, VIN, annual mileage, driving history, and garaging address.
- Request quotes from at least 4 to 5 insurers using identical inputs. Include a mix of national carriers and regional insurers. You can also use a car insurance calculator to sanity-check your estimates first.
- Enter all quotes into your comparison spreadsheet.
- Verify discounts. Ask each insurer which discounts are already applied. Bundling, safe driver, and telematics programs can move the numbers significantly. Programs like Nationwide SmartRide and Allstate Drivewise advertise discounts up to 40%, though Consumer Reports found the median actual telematics savings was $120 per year, with some programs averaging $231 to $324.
- Look up AM Best, J.D. Power, and NAIC scores for every company in your shortlist.
- Narrow to your top 2 to 3 options and ask the key questions below before deciding. For more strategies, see our guide on how to lower car insurance.
Key Questions to Ask Each Insurer
- What exact coverages and limits are included in this quote?
- What discounts have been applied, and are there any I may qualify for?
- What is your average claim settlement time?
- Will my rate change significantly at renewal after any new-customer discounts expire?
- How do you handle claims for my specific vehicle make and model?
If you want a comparison-ready snapshot of the top carriers, our best auto insurance companies 2026 guide breaks down rates, ratings, and claims scores side by side.
Frequently Asked Questions
What does "apples-to-apples" mean in car insurance comparison?
Apples-to-apples comparison means requesting quotes from multiple insurers using the exact same coverage types, liability limits, deductibles, and optional coverages. This ensures any price difference you see reflects the insurer's actual pricing, not a difference in coverage levels. Without this standardization, you might unknowingly choose a cheaper policy that leaves you underinsured, which is especially risky given that 33.4% of U.S. drivers are uninsured or underinsured per the 2025 IRC study.
How many car insurance quotes should I get before choosing?
Most experts recommend getting at least 4 to 5 quotes from different carriers. This gives you a representative range of pricing and helps identify outliers, both high and low. Given that State Farm is cutting rates by an average of 10% across 40 states in 2026 while other insurers continue raising premiums in select states, a wider comparison net is essential to capture the true market spread.
Why is the cheapest car insurance quote not always the best?
The cheapest quote may reflect lower coverage limits, higher deductibles, or excluded add-ons that shift financial risk onto you. Additionally, some lower-cost insurers have poor claims handling track records. A policy that saves you $20 per month but delays or disputes your claim could cost thousands more after an accident, which is why AM Best, J.D. Power, and NAIC scores matter as much as price. See our beginner's guide for how to weigh all these factors.
What should I look for beyond the price when comparing quotes?
Focus on three key non-price factors: AM Best financial strength ratings (look for A or higher, noting State Farm's November 2025 downgrade to A+), J.D. Power claims satisfaction scores (industry average 700 out of 1,000, with Erie Insurance leading at 743), and the NAIC complaint index (below 1.0 is favorable, with Nationwide 0.34 and Erie 0.35 among the best). These metrics tell you how reliably the company will perform when you actually need to file a claim. For a full comparison, see our guide to the best car insurance companies.
How often should I re-shop my car insurance for the best rates?
Re-shopping every 12 to 24 months is the recommended frequency for most drivers. However, you should shop immediately after major life events like moving, buying a new car, adding a driver, or getting married. Median annual savings from switching sit around $461 per Consumer Reports, with 92% of switchers saving money per LendingTree, so loyalty typically costs more than shopping.